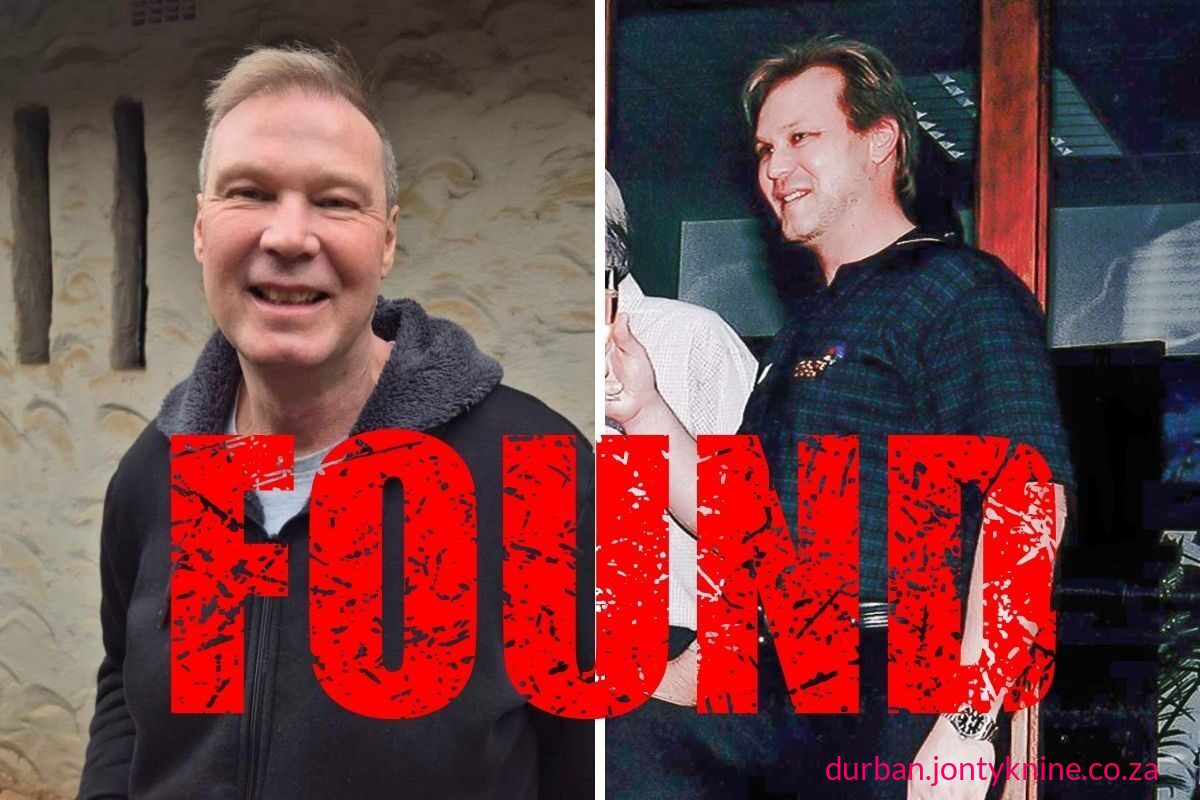
Former Telkom CEO Sipho Nkosinathi Maseko was convicted on 9 October 2026 in the Palm Ridge Magistrate’s Court in his representative capacity as a director of five companies that failed to submit a total of more than 85 tax returns to the South African Revenue Service (SARS).
The companies are:
- One Fountain Properties (Pty) Ltd
- One Fountain Industries (Pty) Ltd
- One Fountain Capital (Pty) Ltd
- Afrifund Advisory Services (Pty) Ltd
- Afrifund Investments (Pty) Ltd
He faced 85 counts of contravening section 234(2)(d) of the Tax Administration Act 28 of 2011. The charges covered failures to submit Pay As You Earn (PAYE), Value-Added Tax (VAT), and Corporate Income Tax (CIT) returns over several years. The National Prosecuting Authority (NPA) stated that Maseko and fellow director Sonwabo Mtshazo were the directors of the entities involved.
The companies paid an admission-of-guilt fine of R85 000. All outstanding returns have since been submitted, allowing SARS to assess them. State Advocate Athenkosi Mancoba argued that the non-submission hampers SARS in administering tax effectively and collecting revenue.
Context and investigation
The case forms part of Project Honey Badger, a joint initiative by the NPA, SARS, and the Directorate for Priority Crime Investigation (DPCI/Hawks). The project aims to improve tax compliance by prosecuting individuals and entities that fail to meet statutory obligations. SARS opened the case in September 2025; it was not a joint investigation and did not stem from a tip-off.
The NPA welcomed the outcome, stating that it “reinforces the importance of complying with tax legislation and reminds taxpayers of their legal obligation to submit tax returns as required by law.”
Background on Maseko
Sipho Maseko served as Telkom Group CEO from April 2013 until the end of 2021 (with his departure brought forward from a planned mid-2022 exit). He previously held senior roles at Vodacom and BP Southern Africa. During his Telkom tenure the company underwent significant restructuring, including staff reductions and a shift toward mobile and IT services (via the Business Connexion acquisition). He received substantial exit-related payments, including retention bonuses totaling around R20 million over two years, which drew shareholder scrutiny at the time.
This conviction is distinct from earlier personal legal matters involving Maseko (such as a 2014–2015 case over allegedly falsified vehicle licence plates that was ultimately dropped, and a Companies and Intellectual Property Commission directive related to a loan granted to a Telkom CFO). Those were separate from the current corporate tax-compliance matter.
Broader implications
South African authorities have intensified enforcement against non-filing of returns through initiatives like Project Honey Badger (and related efforts). Directors can be held personally accountable in a representative capacity even when the companies later regularise their affairs and pay admission-of-guilt fines. Failure to submit returns is treated as a statutory offence under the Tax Administration Act regardless of whether tax was ultimately due, because it prevents SARS from assessing liability.
The relatively modest fine (R85 000 for 85 counts) reflects the admission-of-guilt route once returns were filed, rather than a contested trial or more severe tax-evasion charges involving under-declaration or fraud. Similar recent cases under the same project have involved fines, suspended sentences, or imprisonment depending on the scale, duration, and whether fraud elements were present.